Money Matters Summer 2022
Updates, news and services from lakeside financial solutions
Housekeeping that Pays Off
Sometimes, taking care of small, seemingly insignificant bits of administration and housekeeping can get overlooked, with preference given to dealing with those tasks that seem more urgent in the short term. However, the old saying "a stitch in time saves nine" is just as valid today as it ever was.
Recently we have had significant problems processing investment and pension withdrawals for clients in circumstances where these little bits of housekeeping have been neglected.
When making a withdrawal, advisers and providers have a duty of care to make sure that the funds get paid to their rightful owners. So, whilst fraud is still very rare, it is becoming increasingly sophisticated, meaning providers must carry out more stringent verification to protect your investments.
These checks include making sure that:
- The name on the bank account matches the client's name held by the provider exactly.
- The address the bank account is registered to matches the address held by the provider.
- The name and address on your photo ID (passport/driving licence) match those held by the bank and the provider.
- That your photo ID has not expired.
When this is not the case, providers cannot proceed with a withdrawal until they are satisfied that they are dealing with a legitimate request, which usually requires your details to be updated with various organisations, which can cause significant delays.
"we always do everything we can to process transactions as quickly as possible"
It's understandable that updating your address after a house move, updating your name if you marry, or noticing an error on your statement can get overlooked. We would, however, encourage you to take the time to check that your details are consistent across all of your documents to prevent these delays from becoming a frustration later.
For all clients, regardless of the circumstance, we always do everything we can to process transactions as quickly as possible. However, you can prevent frustrating delays by taking a moment now to review your documentation and check that everything is accurate and up to date.
Finance Q&A - Property Protection Trust in Wills
Putting your share of property into trust in the event of your death will protect both your surviving spouse and your beneficiaries. Lakeside Practice Principal Matthew Hibbert explains how...
What is a property protection trust will?
M: Most couples own their property as Joint Tenants, meaning that there is very little estate planning possible when it comes to the family home. A property protection trust (technically known as an interest in possession trust) is used in conjunction with a severance of tenancy to protect a share of the property from being lost to things such as long term care fees, bankruptcy, means testing, or the remarriage of a spouse following your death.
In the event of the first death, that person's share of their property is placed in trust for the benefit of the spouse or partner, without it being automatically owned by them.
Who is a property protection trust will suitable for, and how does it work?
M: This type of protection is suitable for anyone wanting to give someone the right to live in their house following their death without giving them complete ownership of it.
For example, suppose a couple get together in later life who have children from a previous relationship. In that case, they will likely want their share of their home to go to their own children when they die but wouldn’t want their surviving spouse to be left without anywhere to live.
If a property protection trust exists in a will, it will stipulate that the surviving spouse is entitled to full use of the property for their lifetime (or a stated period), giving security to the survivor to remain in the family home. Meanwhile, the deceased’s share of the property will go into the trust. On the death of the remaining spouse, the ultimate beneficiaries (usually children) receive half the house from the trust and the remaining half from the second death.
The trust is then dissolved, and the beneficiaries own the relevant share of the property.
For further information on property protection trust in wills, please contact: admin@lakesidefs.co.uk
What are the key benefits of having a property protection trust will, and what are the main risks of not having one in place?
M: One of the main reasons people use this type of trust is to protect their share of a property from the assessment of long-term care fees of the surviving spouse. Assets in a trust cannot usually be assessed as available capital to pay such fees.

The trust can also ensure that children of the deceased don’t miss out on a share of the family home if the surviving spouse was to remarry, be declared bankrupt or put their own assets at risk in any way.
Some may question why not give their property share directly to their children in the event of their death? Well, this would mean the surviving spouse would be vulnerable should a child become bankrupt, get divorced or die, as it could force the sale of the property, leaving them homeless.
How can you help clients wanting to explore this type of trust in wills?
M: The estate planning principles are fairly straightforward, but the technicalities should be looked at in detail as part of a wider financial plan relating to the individual’s unique circumstances. We would also make sure that everything makes sense from a tax point of view to avoid any implications.
Preventing Fraud
In today’s digital-dominated world, we are exposed to more fraud risks than ever before.
Therefore, it helps to be aware of the different types of fraud, how to protect yourself from such scams and what to do if you become a victim of this crime.
Fraud occurs when someone uses trickery to benefit from you financially. These ‘fraudsters’ can run sophisticated and convincing scams and target people online as well as via phone call, text and in person.
Phishing emails are often used in an attempt to gain personal information that can lead to identity fraud. These are fake emails that appear to have been sent from a trusted organisation, such as your bank or HMRC. They often want you to click on a link to confirm your security details, revealing this private information to scammers.
Common Types of Fraud
- Identity theft - This occurs when fraudsters access your personal details via social network sites, phishing emails, or thrown out bills and statements. Such information can be used to try to buy goods or take out credit in your name.
- Pension and loan scams - A scammer could contact you to try to get you to transfer the money in your pension, possibly by offering you early access to your funds or a special investment opportunity. Loan-wise, they’ll offer you a fake loan, and in order to ‘approve’ it, they’ll request an up-front fee payment, leaving you without said loan and out of pocket.
- Prize draw scams - Scammers will tell you that you’ve won a prize which is, in fact, fake. To access the ‘prize’, they might ask you to pay an up-front fee, ring a premium rate telephone number or request banking/personal details.
- Council tax refund schemes - In this instance, fraudsters will contact you saying you’ve been put in the wrong tax bracket, and they can help access a refund for a fee or by requesting your personal details.
How to Prevent Fraud
The good news is that there are preventative measures that you can take to avoid becoming a victim of fraud. These include:
- Double-checking who people are before handing over personal information
- Using anti-virus software and avoiding accessing public WiFi connections.
- Being wary of emails asking you to click links and confirm personal information.
- Not including personal details on social network sites.
- Shredding statements/documents containing personal and banking details.
It’s also important to report any missing or stolen bank cards or personal documents so that there is a record of activity should scammers attempt to use them.
There are official bodies that can help you determine fake investment, loan and pension schemes, including The Financial Conduct Authority, and you can register with Action Fraud Alert to receive warnings of current scams known to be circulating.
Regularly checking your bank statements and credit reference file can also unearth fraudulent activity by showing transactions/entries you do not recognise.
In the unfortunate instance that you become a victim of a scam, defraud or cybercrime, you can find full details of how to report it by visiting www.actionfraud.police.uk

An income protection policy will provide you with a regular monthly income if you have to take time off work due to an accident or illness.
This type of cover is beneficial to both employed and self-employed clients and can be tailored to suit your individual needs.
While you can’t predict the occurrence of a serious illness or an accident, having this type of cover in place will give you peace of mind that you can access support should you be unable to work whilst recovering.
Even if you could survive on your savings for several months, would you really want to spend your hard-earned savings on general monthly expenditures? Or to significantly reduce the quality of the lifestyle you are accustomed to?
At Lakeside FS, we can help establish your needs and priorities to find the best income protection solution to suit your circumstances. Simply contact admin@lakesidefs.co.uk to find out more.
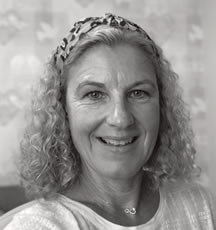
LAKESIDE TEAM Q&A - Julie Roberts
Responsible for client and admin support, Julie Roberts helps keep Lakeside FS running smoothly day to day. Here Julie shares how she assists the team, what she enjoys most about the job and the challenges she sets for herself outside work.
Tell us a little about your background and how you came to join Lakeside
I’ve worked in various roles in the past, including helping clients to put in place home insurance, and within an admin role at Burntwood Hotel in Barnsley.. Most recently, I managed the Longfields Court business centre, where Lakeside’s offices are located, which is how I came to hear of this position. I was ready for a new challenge, so the opportunity came at the perfect time!
What is your role at Lakeside, and what does it entail?
I joined the team in March 2021 as client and admin support based at the Longfields Court office. It was during Covid restrictions which added to the usual challenges of settling into a new role, but thankfully it didn’t take me long to find my feet. Day to day, I help to keep everything ticking along at Lakeside FS, from chasing up providers and dealing with post to arranging will-related documents to be sent out to clients.
What do you enjoy most about the job?
I love how friendly the team is. It’s a really relaxed and supportive environment to work in, so I’ve enjoyed getting back to the office after Covid restrictions were lifted. I’m also fortunate that my pet Labrador Retriever, Barney, comes to work with me, giving me a reason to get outdoors on my lunch break and meaning I’m refreshed for work in the afternoon.
Tell us about your main interests away from work?
I really enjoy running with my daughter. We’re part of Ackworth Road Runners and often take part in running events, mostly 10ks and half-marathons. Me and my husband have a campervan, so we love being able to get away in that with Barney too!
What are your personal goals for 2022?
I’ve got two half-marathons to come in the next few months - The Great North Run and a local event in Pontefract - so I’ll be aiming to keep up my training and add completing those events to the fitness challenges I continue to set for myself.
Can you share your personal and work goals for 2022?
My work goal for 2022 was to pass my Level 6 to obtain Chartered Status, which I achieved in January, getting the year off to a great start! My personal goal will be to climb Matterhorn - one of the highest summits in Europe - during a trip to the Alps later this year. I’m also planning to get back into cycling.
If you would like to discuss Lakeside’s investment and estate planning services, contact the office at admin@lakesidefs.co.uk
SERVICES
Just some services we offer at Lakeside
At Lakeside our clients benefit from bespoke financial solutions and pro-active, ongoing advice as well as access to exclusive products and services with extremely competitive pricing and charge caps. We offer the following services to all our customers:
- Investments
- Pensions
- Insurance
- Mortgages and Lending Options
- Wills
- Lasting Powers of Attorney
Visit the ‘News’ section of our website for further articles and updates on the portfolio of services that we offer.