Money Matters Autumn 2022
Updates, news and services from lakeside financial solutions
Let’s Talk Debt Consolidation
With the cost of living continuing to rise, every pound counts. For those with debt, consolidation could provide a timely solution to free up more cash to cover increasing household bills.
It’s impossible to ignore that the cost of living is rising, with hikes in energy bills and fuel and food costs impacting households across the country.
According to a study published by the Office for National Statistics, using data from the Opinions and Lifestyle Survey, 87% of adults reported an increase in their cost of living in the month of March 2022. In addition, nearly a quarter of adults said it was ‘very difficult’ or ‘difficult’ to pay their usual household bills compared with a year ago, and 43% reported that it was ‘very’ or ‘somewhat difficult’ to afford their energy bills.

87% of adults reported an increase in their cost of living in the month of March 2022

17% of adults reported borrowing more money or using more credit than they did a year ago
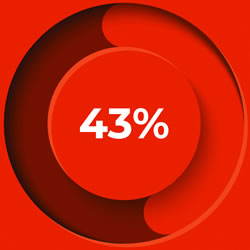
43% reported that it was ‘very’ or ‘somewhat difficult’ to afford their energy bills
In the same survey, 17% of adults reported borrowing more money or using more credit than they did a year ago.
As we head into the colder winter months, pressure on households will only likely increase as gas bills continue to rise. Unfortunately, we can’t predict when the current situation will improve, but we can help get your finances in order to better manage everyday bills and unexpected costs.
For those with multiple debts, consolidating could be a welcome solution to save time and stress while freeing up money to cover those increasing household bills.
Consolidating debt is the process of switching some or all of your existing debt - incurred through loans, overdrafts and credit/store cards etc. - into one new loan. This means you will owe money to fewer lenders and have fewer direct debits going out each month. Often for clients, this will be a case of extending your mortgage borrowing to consolidate your unsecured debts.
Mortgage borrowing tends to carry lower interest rates than unsecured borrowing and often has longer repayment terms available. This will generally result in lower monthly repayments, making your finances more manageable and increasing your disposable income each month, which will help cover those everyday living costs and bills.
Debt consolidation isn’t without risks though - primarily, securing debt against your home means the property is at risk if you don’t keep up with your repayments. This is why it’s important to take professional advice on these types of transactions.

For clients wanting to explore debt consolidation, we would look at your individual situation and what you would like to achieve and then put together a financial plan to help get you there. It may be that there are alternative options to debt consolidation, such as taking out a personal loan to pay off outstanding credit card debts, but we would explore that as part of our research and make a recommendation on the best course of action.
For further information on debt consolidation, please contact: admin@lakesidefs.co.uk
Finance Questions & Answers
Property Protection Trust in Wills
Discretionary trusts in wills pass decisions on how and when your estate is distributed to a trustee, who makes judgement calls on your behalf following your death. Lakeside Practice Principal Matthew Hibbert talks through the process as well as potential pros and cons.
What are discretionary trusts in wills?
M: A discretionary trust is when your money or assets are left in a trust following your death. Management of the trust is placed in the hands of trustees that you appointed to distribute the inheritance to your chosen beneficiaries in line with your wishes but as they see fit.
Who might they appeal to, and how do they work?
M: This type of trust often appeals to those who want some flexibility over how and when the inheritance is distributed to beneficiaries depending on their circumstances. So, for example, with a traditional will, you could stipulate that a beneficiary receives their inheritance on their 18th birthday; however, you have no way of knowing what their mental or financial state will be at that time.
A discretionary trust would allow a trustee to make a judgement call at that point on your behalf, deciding what would be given to the beneficiary and when. This type of will can also help protect inheritance in the case of divorce. If the money is in trust, it could be excluded from any divorce settlement.
What are the main advantages of discretionary trusts in wills, and are there any disadvantages?
M: The top advantage is the flexibility that the trust allows, giving trustees the discretion to make decisions as they see fit rather than on a predefined timeline. In doing so, they can help beneficiaries plan for the future and avoid the inheritance leaving the bloodline.
Another advantage is that trusts provide lots of flexibility for generational financial planning, where descendants can use the features of the trust to reduce tax bills and make the most of their own planning. We find we add most value when we deal with the whole family, and trust planning is a key area.
In terms of disadvantages, you must take care not to place trustee power in the wrong hands. Therefore, it’s important to choose trustees you trust eternally and who will have your beneficiaries’ best interests at heart. Sometimes, the trustees might even be the beneficiaries themselves; however, it’s important to be cautious when doing this, or it could result in them making decisions purely for their own gains.
"The top advantage is the flexibility that the trust allows, giving trustees the discretion to make decisions as they see fit rather than on a predefined timeline."
How can Lakeside assist clients wanting to explore this type of trust in wills?
M: We would talk through the tax implications and benefits and help you select the best trustees to ensure they couldn’t abuse their position. If this type of trust is set up blindly, the money could go to the wrong people, so we would make sure the document is structured correctly.
For further information on discretionary trusts in wills, please contact: admin@lakesidefs.co.uk
Ask your advisor for a copy of our trust guides
Did you know?
Private medical insurance can cover the cost of and speed up accessing treatment for various illnesses and injuries.
By avoiding NHS waiting lists, you will be seen by a medical professional much quicker, making your condition less likely to worsen while you wait. Additional benefits can include options of where you receive treatment and access to private hospital rooms. Some providers also offer perks such as digital doctor appointments.
You can take out an individual policy, a joint policy for you and your partner or a whole family policy. What is covered varies from provider to provider. Typically it covers inpatient and outpatient treatment, plus the option to extend the cover to include extras like physiotherapy, dental and psychiatric treatment as well as treatment for specific illnesses.
There isn’t a massive choice of providers, but we can help match you to the best one to suit your needs, looking at any existing conditions whilst aiming to safeguard you against others in the future.
For further information on private medical insurance, please contact: admin@lakesidefs.co.uk
LAKESIDE TEAM Q&A - Kalie Hartley
Since joining the Lakeside team in 2016, Operations Director Kalie Hartley has undertaken a number of roles to grow and evolve with the company. Here, she shares the key responsibilities of her current position and explains what sets Lakeside apart from the rest.
Tell us about your background and how you came to join Lakeside?
I initially worked my way up through Barclays Bank. I started as a cashier in the Huddersfield branch, then worked my way up to Assistant Manager and Branch Manager at Barnsley, then Doncaster, before becoming Market Leader looking after eight branches in the Hull area.
I had to undergo spinal surgery and so could no longer do the drive to Hull, which forced my hand in looking elsewhere, though it turned out to be the best thing I ever did!
What is your role at Lakeside, and what does it entail?
I joined the team in March 2021 as client and admin support based at the Longfields Court office. It was during Covid restrictions which added to the usual challenges of settling into a new role, but thankfully it didn’t take me long to find my feet. Day to day, I help to keep everything ticking along at Lakeside FS, from chasing up providers and dealing with post to arranging will-related documents to be sent out to clients.
When did you join the company, and what attracted you to it?
I joined in July 2016 after having met some of the team. I was really impressed that Lakeside maintained the feel and ethics of a small family-run firm whilst offering a wide range of different financial solutions that would ordinarily be accessible to a much larger company.
How has your role changed over the years?
I originally joined Lakeside as a Financial Consultant, but when I had to undergo further surgery on my spine, this was no longer viable.
Myself and Nathan sat down and discussed what roles I could take on moving forward based on my work history at the bank. The role began initially with doing some compliance and operations work and focussing on the recruitment and training of mortgage and protection advisers. This is still the case today, but the role has grown and evolved along with the company and so now includes helping out with the day-to-day running of the firm, looking after the team of both employed and self-employed advisers, and generally making things happen!
What do you enjoy most about your job?
Working with a team of incredibly talented people who genuinely put the customer at the centre of everything they do.
And what sets Lakeside apart from other financial companies?
The difference is that we focus on ‘holistic’ planning with our clients to ensure we put them in a better position both now and in the future. We don’t want to have a purely ‘transactional’ relationship with clients; we want to work with them over the long term to achieve their goals and objectives throughout their lifetime.
Tell us about your main interests away from work?
Honestly, I’m pretty much a workaholic, so often, when I get a spare few minutes, I’ll pick up the laptop. I enjoy it so much that it doesn’t seem like work. If you do see me without my laptop, it’s usually spending time with my friends and family or walking my giant puppy, Quinn.
What are your top personality traits?
I’m very driven and have a strong work ethic, but I’m also very caring and love to have a laugh.
Can you share a goal that you've achieved so far this year?
Completing the Yorkshire Three Peaks Challenge in July. Before my back surgeries, I did this walk annually, but this is the first time I’ve managed to walk all three peaks since.
If you would like trusted financial advice; from mortgages and investments to planning your retirement, contact the office at admin@lakesidefs.co.uk
SERVICES
Just some services we offer at Lakeside
At Lakeside our clients benefit from bespoke financial solutions and pro-active, ongoing advice as well as access to exclusive products and services with extremely competitive pricing and charge caps. We offer the following services to all our customers:
- Investments
- Pensions
- Insurance
- Mortgages and Lending Options
- Wills
- Lasting Powers of Attorney
Visit the ‘News’ section of our website for further articles and updates on the portfolio of services that we offer.

