
Autumn Newsletter 2026
On the day of the recent solar eclipse I had to have an awkward conversation with my 8 and 12 year old kids. Some of their friends at school were watching the eclipse directly using their special eclipse glasses which their parents had bought online in preparation for the event.
Unfortunately, in our household, we had left everything a little bit late. By the time I looked on Amazon to buy some glasses it was a few days before the big event, and the quickest delivery was 3 weeks away (given that the next significant eclipse won't be until 2090 I didn't bother). This left our kids watching the eclipse through pinhole projectors and colanders.

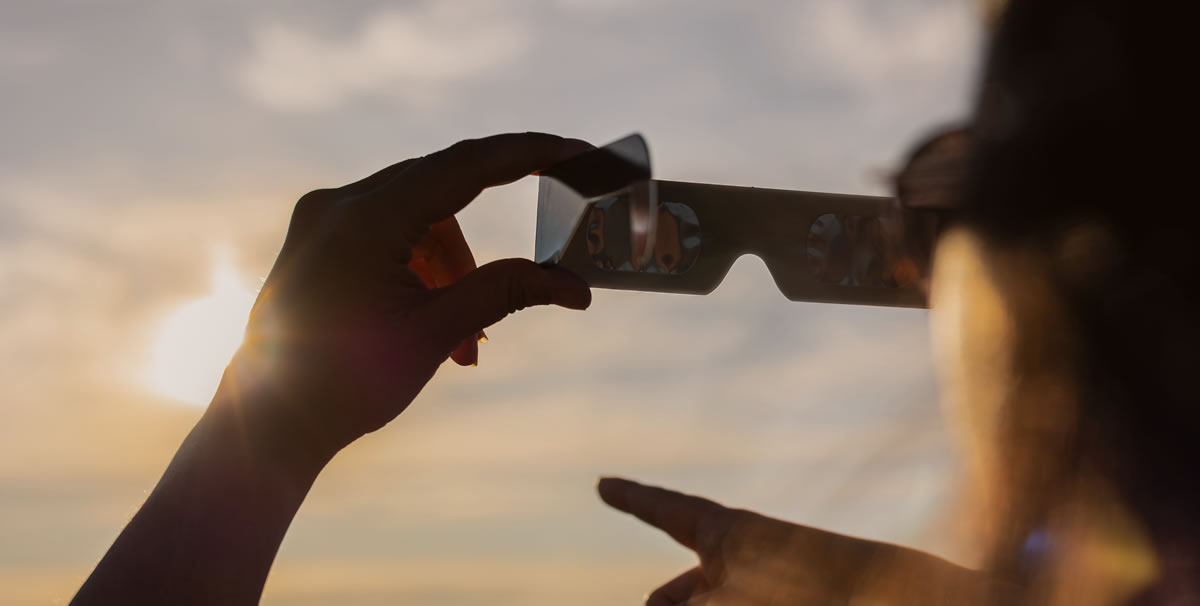
When it comes to saving for retirement, those who plan early, can make relatively affordable contributions into their retirement savings
When speaking to other parents in the days after, I found that they fell into three broad categories.
The first group had planned early, bought the glasses online at a reasonable price and were able to enjoy the eclipse fully and safely.
The second group were only marginally better than me – they had left it quite late to search, which had made it more difficult to track down the glasses and meant they were paying way over the odds compared to the people who had got themselves organised. Some only managed to get one pair to share between the family, it was a relatively expensive experience – but they got there in the end.
The third group, my group, and by far the largest group were the people who left it so late to start planning, that there was no realistic way to enjoy it properly. We were left improvising… or ultimately, just not bothering.
If I'm honest, I felt the eclipse was a bit of a let-down in the end - but it did get me thinking about the parallels with retirement planning.
When it comes to saving for retirement, those who plan early, can make relatively affordable contributions into their retirement savings. The combination of time and compounding investment growth can give them a comfortable retirement at a relatively low cost.
PENSION CHANGES FOR 2027
This change represents a good opportunity for you to update your nomination regarding who should receive your pension in the event of your death. This can be a spouse, children, wider family, or any individual(s) you choose.
For clients who intend to leave their pension to a spouse or partner, we are recommending that they also consider naming any children as beneficiaries with a nominal allocation. For example:

While these amounts may appear token, they serve an important purpose: by including children on the form, the pension trustees are given the flexibility to reallocate funds between beneficiaries if requested. This could prove useful in reducing the income tax and inheritance tax burden on your estate and your family after your death.

It is worth noting that this approach does come with a small trade-off. Adding children to the nomination means the pension will no longer pass exclusively to your spouse, which may not suit everyone's circumstances. Additionally, any funds directed to children would not benefit from the spouse exemption that can defer inheritance tax on death. For most clients, however, the added flexibility outweighs these considerations - and the nominal percentages can always be adjusted or removed by simply updating the form at any time.
We will be emailing all clients about this recommendation over the coming weeks. Please review the email when you have received it, and let us know if you have any questions.
As always - your adviser will be happy to talk through whether this approach is right for your situation at your next review.
For more information on Lakeside services, please contact: admin@lakesidefs.co.uk
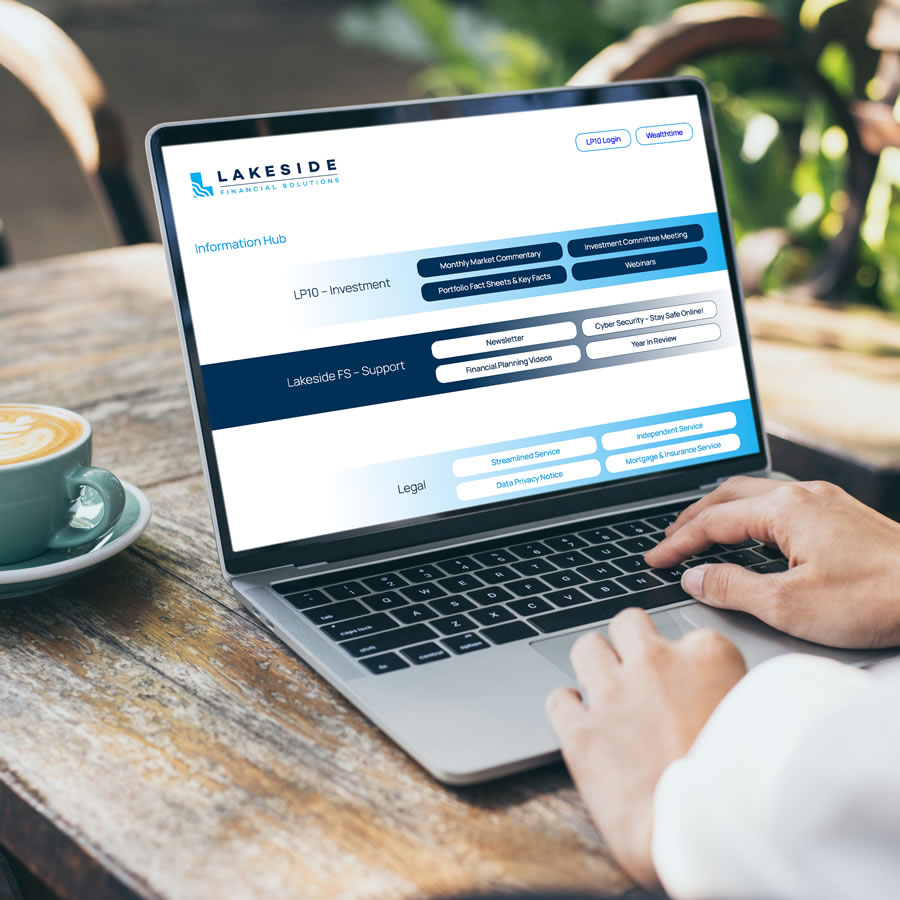
Over recent months we have been gradually moving a lot of our documents and communications into our new client portal.
The portal includes things like:
- Links to log into the investment portal
- Newsletters
- Investment committee updates
- Webinar recordings
- Disclosure documents
- Portfolio Fact Sheets
You can access the portal by visiting: client.lakesidefs.co.uk
SERVICES
Just some services we offer at Lakeside
At Lakeside our clients benefit from bespoke financial solutions and pro-active, ongoing service as well as access to exclusive products and services with extremely competitive pricing and charge caps. We offer the following services to all our customers:
- Investments
- Pensions
- Insurance
- Mortgages and Lending Options
- Wills
- Lasting Powers of Attorney
Visit the ‘Information Hub’ section of our website for further articles and updates on the portfolio of services that we offer.
