
FINANCE QUESTION AND ANSWERS
FAMILY INCOME BENEFIT LIFE INSURANCE
 Family income benefit life insurance helps ensure your loved ones can maintain the lifestyle they’re accustomed to following your death via regular payouts to cover ongoing bills and living costs. Lakeside Financial Consultant Rebecca Venton explains how such policies work and their key benefits.
What is family income benefit life insurance?
R: Family income benefit is a special type of life cover, which will pay out a regular (monthly or annual) income to your loved ones for a set period to ensure that they do not have a shortfall in income if you pass away.
Who is this type of policy best suited to, and what are the key benefits of this type of life insurance compared to other options?
R: This type of policy is best suited when you feel your loved ones would benefit more from a regular income rather than a large windfall. It is often recommended when children are involved, as it would allow them to maintain the lifestyle they are accustomed to, whether with a sole surviving parent or with guardians.
This type of cover is often referred to as ‘guardianship protection’. Family income benefit may also be recommended as a multi-benefit plan, for example, with a fixed term decreasing life plan to cover a mortgage element.
Other options, such as level or decreasing term life cover, may be appropriate where there is a large debt, such as a mortgage or other loans to repay. These types of life cover are also set on a fixed term, as is the family income benefit.
If you wanted to ensure your family would have a pay-out at any point in time - perhaps in later life or for funeral expenses - then a whole of life plan may be more suitable.
How long does family income benefit pay out for, and can the policy be put into trust?
R: Family income benefit would pay out until the end of the chosen term. For example, if you passed away two years after putting in place a 30-year plan, it would pay the benefit amount annually or monthly for the remaining 28 years. If you passed away 28 years into the plan, the benefit amount would be paid for the remaining two years.
All life insurance policies can be written into trust. This is a legal arrangement that is free and essentially means the policy is viewed as being outside your estate, potentially leading to a quicker payout for your loved ones.
What key considerations would you advise clients to think about when taking out family income benefit life insurance? How can Lakeside assist with such?
R: A key consideration is whether or not your loved ones could survive without your household income. Although they may have life cover which may allow them to repay debts, such as a mortgage, this doesn’t put food on the table or buy school uniforms, etc.
It’s also really important to consider that you may have named friends or family members to act as guardians for your children if you were to pass away. Would these guardians be in a position financially to provide and maintain the same lifestyle that your children are used to without an additional income? If the answer to this is no, you should consider putting in place a policy to ensure that they can.
At Lakeside, we take time to understand your situation, needs and objectives and would build a recommended solution personalised to your situation.
Please feel free to contact us for further information: admin@lakesidefs.co.uk
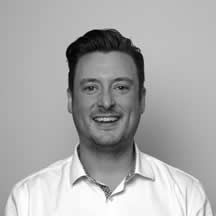 LAKESIDE TEAM Q&A - James Foster
Financial Adviser James Foster joined the Lakeside team in 2017, keen to work in a client-facing role and help in creating truly tailored plans. Here, he shares what he enjoys most about the world of finance and outlines the areas in which he can assist clients.
Tell us about your background and how you came to join Lakeside.
Following uni, I had some time thinking about what I wanted to do as a career and was drawn to banking and becoming a financial adviser. Securing a cashier job at HSBC, I quickly worked my way up - I think partly because they were keen to get me away from the desk as I chatted way too much! I got into a specialist mortgage role that I really enjoyed and would have stepped up to manage a team, but I wanted to remain client-facing. So after a spell contracting, I joined Lakeside as a financial adviser and haven’t looked back.
Can you give us a brief overview of your role and your job day to day?
I’m a level-4 qualified financial adviser dealing with everything from mortgages and insurance to pensions and wills.
A lot of my time is spent meeting with clients. For new clients, this would involve understanding their circumstances and their financial objectives and putting tailored plans in place. For existing clients, this will be reviewing any changes to their circumstances and helping things remain on track. When I’m not with clients, I’ll normally be looking over their files and formulating strategies.
What do you enjoy most about it?
As a naturally sociable guy, my favourite part of the job is meeting clients. It’s really rewarding to come up with a financial plan suited to their circumstances, which will make a real difference to their lives.
Tell us about your main pastimes away from work?
Family time is really important to me, so days out, meals, and walks with my wife Alex and the kids. Also, supporting Huddersfield Town. I’m a season-ticket holder and pretty much never miss a game - which has often landed me in trouble with Alex!
What are your personal and work goals for the remainder of 2021?
I hope to make up for lost time and see much more of our family and friends. I started doing more fitness in lockdown, so I’m striving to keep up with my running too. Workwise, my goal is to maintain the improvements I’ve made in keeping in regular contact with existing clients.
Finally, what areas can you assist clients in?
I can help with most matters related to money, including investments, pensions, insurance, mortgages and lending options, wills, trusts and lasting powers of attorney.
If you would like to discuss Lakeside’s investment and estate planning services, contact the office at admin@lakesidefs.co.uk
SERVICES
Just some services we offer at Lakeside
At Lakeside our clients benefit from bespoke financial solutions and pro-active, ongoing advice as well as access to exclusive products and services with extremely competitive pricing and charge caps. We offer the following services to all our customers:
- Investments
- Pensions
- Insurance
- Mortgages and Lending Options
- Wills
- Lasting Powers of Attorney
Visit the ‘News’ section of our website for further articles and updates on the portfolio of services that we offer.
