Autumn Newsletter 2025

PREPARING FOR SUNNY DAYS
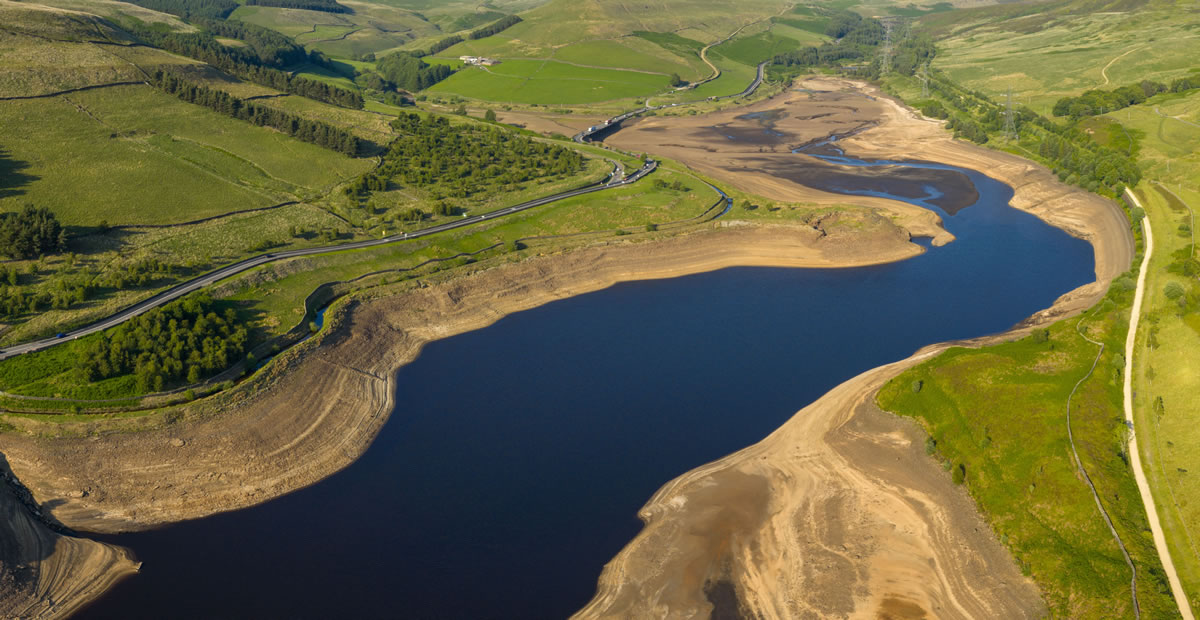
In recent weeks, Yorkshire Water has announced a hosepipe ban to reduce water usage and protect critically low water levels. As is often the case the debate now rages over the need for a ban, the cause, and what or who is to blame.
There’s no doubt that the weather has changed over recent years, with our summers getting dryer; but wetter winters mean that the overall annual rainfall in the UK is actually increasing. So, if there’s more rain overall, it follows that part of the problem is that our storage capacity hasn’t kept pace with increasing use.
In other words, we aren’t saving enough water when it is raining, to meet our needs when it is not, and this is partly because we haven’t built any new storage capacity in the last 30 years.
We often see the same principals at work in financial planning. As people reach retirement, more time for holidays and leisure leads to increased spending opportunities – but they no longer have the income supply which was available when they were working. The rain has stopped, the sun is out, but they are faced with living on what they stored in their financial reservoirs over the previous 30 years – and in many cases, those reservoirs are too small and too shallow.

Preparing for the sunny days
The problem is that many people allow most of their “financial rain” to run away in day-to-day spending on lots of little things which add little real value to their lives. Then, having not stored up a reservoir of savings, people often end up living a “hosepipe ban” retirement – unable to water the grass at a time when it most needs it.
Building up those reservoirs (both literally and metaphorically) requires careful forward planning and sacrifices now to provide for a more secure future. It’s simple, but it’s not easy, as different priorities fight for a share of your income. But just like with the hosepipe ban, the only way to resolve a shortage once you arrive at retirement is to impose unwelcome restrictions.
Financial planning is all about doing what can be done today to secure your future. Helping you to understand how to build up those financial reserves in the most tax efficient way, to maximise the impact of the money you can set aside, then, in retirement helping you understand how those reserves can be used effectively to best serve your needs.

As I watch my grass turning brown and the car getting dirtier, I wish that Yorkshire Water had worked harder on fixing the leaks, building up the storage capacity and preparing for summer. But it should also be a reminder to us all that the sunny days of retirement are coming, and we can determine how free we can be when it comes by careful planning and decision making today.
For more information on Lakeside services, please contact: admin@lakesidefs.co.uk
Proven market leader - Over 10 years developing a proposition that independent comparisons confirm is unmatched in cost, performance, and value.
Outperforming the competition - Even the UK’s largest pension and investment providers admit they can’t match us in any single area.
Exceptional value - Combining extremely low costs with strong, risk-adjusted returns through our Discretionary Management service.
Trusted by discerning clients - Independent reviews from other well-known advice firms confirm they cannot equal what we deliver.
VALUE AT EVERY LEVEL
The proposition we have built at Lakeside over the past 10 years is market leading.
We often tell our clients that, based on our research of the market, the proposition we have built at Lakeside over the past 10 years is market leading. However, we are increasingly receiving confirmation of this outside of our normal checks and research.
One such example occurred recently when we were approached by a representative of one of the UK’s largest and most well-known pension and investment providers. She explained that her head office had specifically asked her to speak to Lakeside because of their growing frustration that their products didn’t form a major part of our proposition despite us being on their “hit list”.
This company prides itself on combining extremely low costs with strong investment returns and she was keen to see how our proposition compared.
Having heard the pressure, she was under to speak to us, and knowing her quite well from various discussions over the years, I spent a little time with her discussing the proposition.
As we discussed our Platform and fund costs, she began to sound disappointed. Then as we moved onto the investment performance and risk adjusted returns provided by our Discretionary Management service - disappointed became dejected. She ended the call by saying “I just don’t understand how you are able to offer what you are offering at the price your clients are paying… it’s not just that you are better overall” she said, “we don’t even come close in any individual area.” She ended the call by thanking me for my time, but explaining she was going to have a very difficult conversation when she had to explain what we were doing the next day.
This is just one example of three I’ve had in the last few weeks. In another case, a client had asked two very well-known advice firms to review their investments. However, having completed the review and against their own interest they had to confirm that they were unable to match what we were providing.
For us, this is a huge confirmation of what we already believed to be true – that the products and services we offer to clients are incredibly difficult, if not impossible to match.
Sometimes, taking care of small, seemingly insignificant bits of administration and housekeeping can get overlooked, with preference given to dealing with those tasks that seem more urgent in the short term. However, the old saying "a stitch in time saves nine" is just as valid today as it ever was.
We’ve recently undertaken a mailout to a specific subset of the client bank and had a large number of letters returned because the client no longer lives at the address we hold. Making sure you update your details with us as things change significantly reduces the risk of delays when we come to provide you with important information, or when you come to make withdrawals from your plan – since anti-money laundering and anti-fraud checks carried out by the provider rely on accurate information.
A periodic review of things such as:
- Have you informed us of any changes to your personal details
(address, email, phone, name change etc…) - Does the name on you bank account match the name held by the provider exactly
- Is the address on your bank account the same as the address held by the provider
- Does the name and address on your photo ID (passport/driving licence) match those held by the bank and the provider
- Has your photo ID expired
It's understandable that updating your address after a house move, updating your name if you marry, or noticing an error on your statement can get overlooked. We would, however, encourage you to take the time to check that your details are consistent across all of your documents to prevent these delays from becoming a frustration later.
For all clients, regardless of the circumstance, we always do everything we can to keep in touch and to process transactions as quickly as possible. However, you can prevent frustrating delays by taking a moment now to review your documentation and check that everything is accurate and up to date.
For more information on Lakeside services, please contact: admin@lakesidefs.co.uk
SERVICES
Just some services we offer at Lakeside
At Lakeside our clients benefit from bespoke financial solutions and pro-active, ongoing service as well as access to exclusive products and services with extremely competitive pricing and charge caps. We offer the following services to all our customers:
- Investments
- Pensions
- Insurance
- Mortgages and Lending Options
- Wills
- Lasting Powers of Attorney
Visit the ‘Information Hub’ section of our website for further articles and updates on the portfolio of services that we offer.